FERC Account 362: Distribution Station Equipment
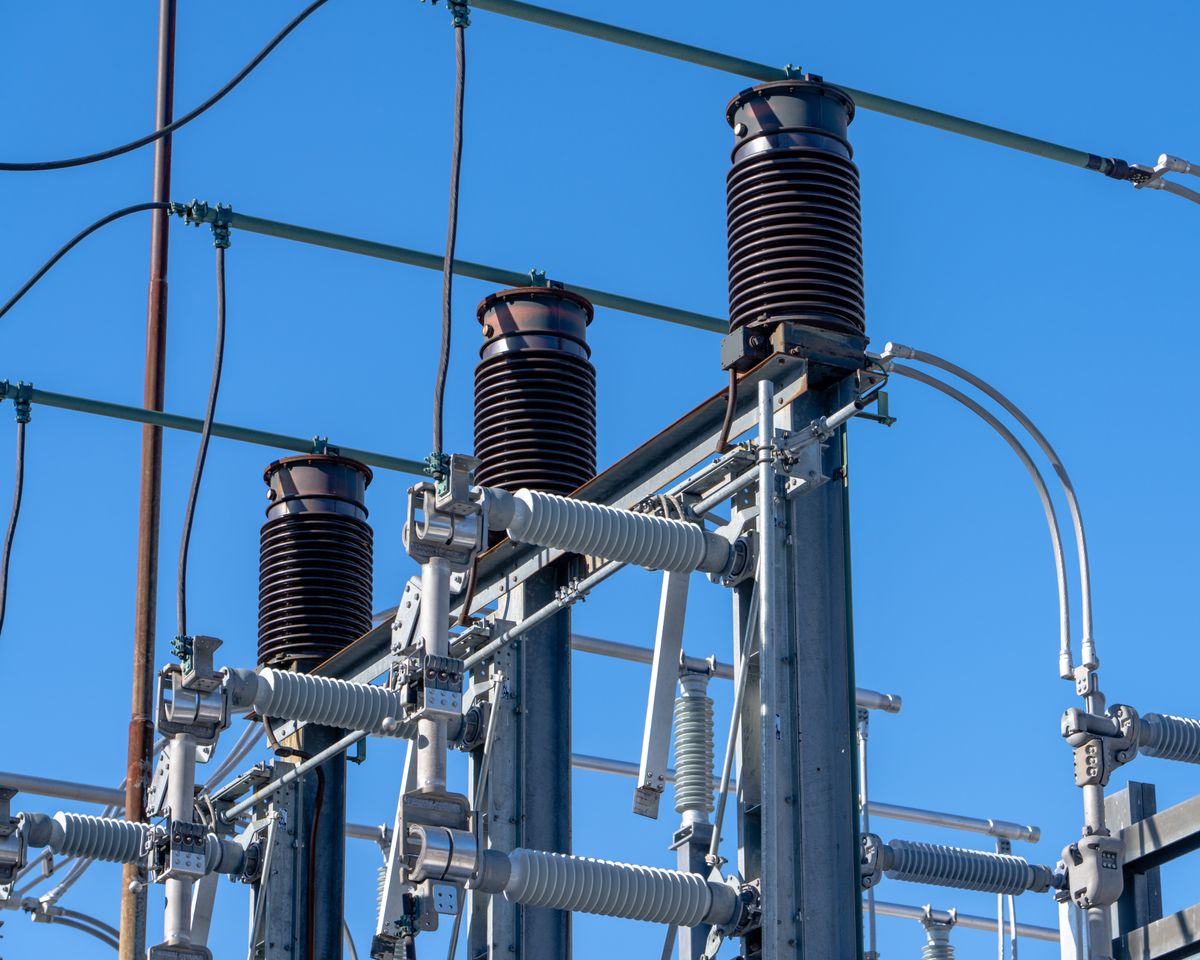
FERC Account 362 is used to record the installed cost of electric distribution station equipment.
Definition
Record in this account the cost installed of electrical equipment located in distribution stations and substations.
Account 362 generally captures the electrical plant installed in distribution substations, including transformers, breakers, switches, bus work, protective devices, and related equipment that transforms, controls, and protects power before it moves onto the distribution system.
What is typically included
- Power transformers, circuit breakers, switches, and bus structures in distribution substations
- Protective relaying, voltage regulators, capacitors, and associated electrical equipment
- Control panels, batteries, chargers, and station electrical apparatus when properly classified here
- Foundations and supports that are integral to the equipment when required by accounting practice
- Installed costs, including direct labor and capitalizable overheads, when applicable
What is generally not included
- Land and land rights recorded in Account 360
- Structures and improvements recorded in Account 361
- Overhead line poles, conductors, and devices recorded in Accounts 364 and 365
- Routine maintenance, testing, and repair expense
- General office or shop equipment not part of the station installation
Why Account 362 matters
- Station equipment is often one of the most significant distribution plant balances on the books
- Proper classification supports accurate depreciation and retirement accounting
- Substation additions and upgrades materially affect rate studies and capital planning
- Clear separation from buildings and line plant improves reporting consistency
Utilities should apply their own capitalization policy, retirement procedures, and continuing property record practices when determining the final accounting treatment for a specific project or transaction.
Examples
Substation transformer installation
A utility installs a new distribution substation transformer and related switching equipment. These costs would generally be capitalized to Account 362.
Breaker replacement project
A utility replaces aging breakers as part of a capital reliability project. If the work meets capitalization policy, the installed replacement cost would generally be recorded in Account 362.
Routine testing
Periodic relay testing and normal maintenance activities would generally be charged to expense rather than Account 362.
Related FERC distribution plant accounts
- Account 360 – Land and Land Rights
- Account 361 – Structures and Improvements
- Account 363 – Storage Battery Equipment
- Account 364 – Poles, Towers, and Fixtures
- Account 365 – Overhead Conductors and Devices
Related Articles